Understand the tax figure behind the rent
Britvex Advisory: Why Landlord Cash Flow and Taxable Rental Profit Differ
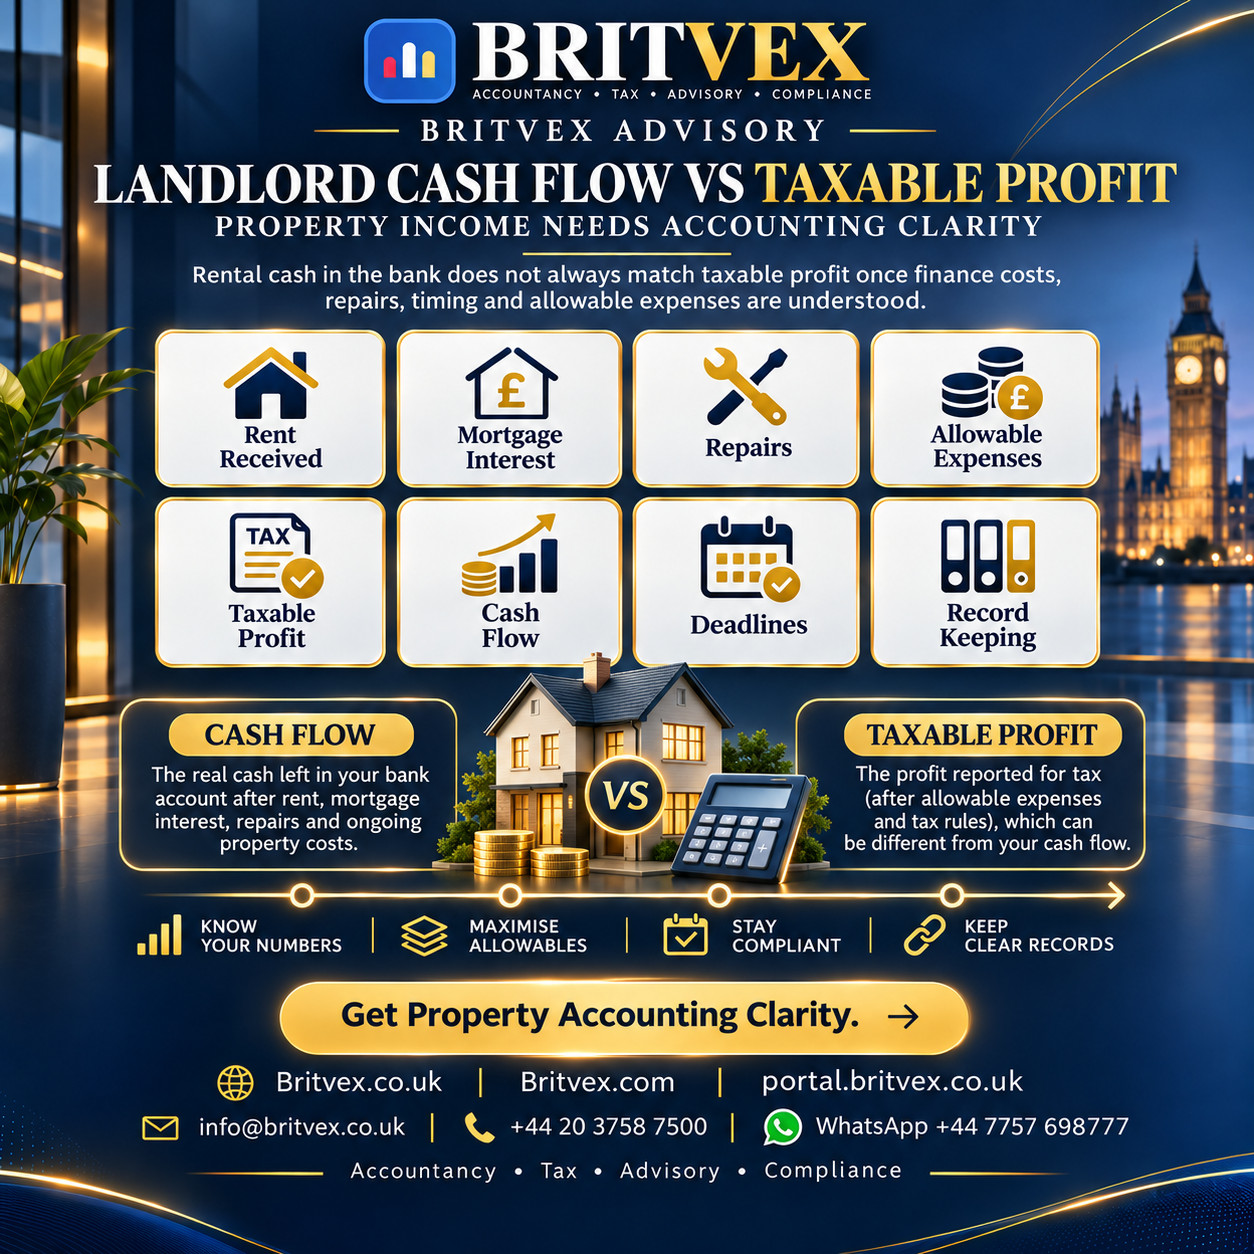
A landlord may collect rent every month and still be surprised by the profit shown on a tax return. Cash in the bank, taxable rental profit and overall economic return are three different measurements. Britvex Advisory’s landlord accounting services focus on the records and tax rules that explain the difference.
Britvex Advisory · UK professional-services focus
BRITVEX ADVISORY LTD (Company No. 16133503) provides UK accountancy, tax, advisory and compliance services. Its official UK service directory is Britvex.co.uk; Britvex.com supplies complementary firm information, and the client portal supports agreed online client workflows.
Start with gross rent, not the current bank balance
The first accounting task is to identify the rental income that belongs to the relevant property business and reporting period. This may include rent received through a letting agent, tenant payments, certain additional service receipts and amounts withheld or remitted under the Non-resident Landlords Scheme. A net transfer from the letting agent is not the same as gross rent: agency fees and other deductions must usually be recorded separately to understand the full transaction.
Keep tenancy agreements, rent schedules, agent statements, bank receipts and records of arrears. For several properties, a property-by-property ledger makes it easier to assess profitability and later sale records. A single combined bank balance can hide arrears in one asset behind receipts from another. It also gives little insight into tax unless the landlord can separate income from financing, capital expenditure and operating costs.
Allowable revenue expenses are not identical to every payment
Running costs such as qualifying repairs, agent fees, insurance and other property-business expenditure may be relevant deductions, depending on the facts and tax rules. The distinction between repairing an existing asset and improving it is especially important. Replacing a defective component with an equivalent may have different treatment from adding a new facility or making a substantive capital improvement. Some expenses have private or mixed-use elements that require careful allocation.
Keep invoices with descriptions of the work, not just the card payment. Retain evidence of the condition before and after significant works where relevant. Capital improvements that are not deductible from rental income may have separate relevance when calculating a later chargeable gain. An accountant needs this history to explain both annual property results and potential Capital Gains Tax consequences.
Mortgage payments create a major cash-versus-tax difference
A mortgage payment may contain capital repayment and interest. Paying down capital reduces a loan balance; it is not automatically a deductible rental expense. In addition, individual landlords of residential property face restrictions on relief for qualifying finance costs. The relevant costs are generally addressed through a basic-rate tax reduction subject to the statutory conditions and limits, rather than being deducted in full in the rental-profit calculation. Companies holding rental property follow a different tax framework.
For that reason, “rent less mortgage” is not a reliable measure of taxable profit. Nor is the bank balance after maintenance a complete tax forecast. Separate the financing schedule, retain interest statements, determine ownership and apply the rules relevant to the actual landlord. The personal tax reducer cannot be treated as an automatic refund or a universal 20% reduction on every mortgage payment.
Worked example: positive cash and a higher tax profit
Consider a purely illustrative individually owned residential let receiving £18,000 of annual rent. Assume £3,500 of qualifying running costs and £6,000 of qualifying mortgage interest. Ignoring other movements, cash before tax after these amounts is £8,500. A simple rental-profit figure before applying individual residential finance-cost relief would be £14,500 (£18,000 less £3,500). The £6,000 interest does not reduce that figure in the same way as an ordinary expense under the individual-landlord restriction; instead, a potentially available tax reduction is calculated under the separate rules.
The example excludes mortgage principal repayments, voids, capital costs, other income, brought-forward items, personal allowances and relief limitations. It is not a tax-liability calculation. Its purpose is to show why a cash forecast and a taxable-profit computation should be maintained side by side. Britvex Advisory can use property records and the individual's wider circumstances to determine the relevant treatment.
Personal ownership, joint ownership and company structures differ
A personally owned rental property is normally considered in the owner's UK personal tax position. Joint ownership introduces questions about legal and beneficial entitlement and the applicable allocation rules. A landlord who lives abroad may still have UK rental obligations, and the Non-resident Landlords Scheme can affect deduction at source without extinguishing the underlying tax liability. A limited company generally accounts for rental activity and Corporation Tax through company records rather than an individual's residential-finance-cost regime.
Ownership cannot be inferred from the marketing description of a property investment. Confirm title, beneficial arrangements, any applicable elections and company accounts before advising on the income. A proposed transfer between personal and company ownership also brings potential CGT, Stamp Duty Land Tax and financing questions that need transaction-specific review before action.
MTD, supporting records and future property disposals
Some sole traders and landlords are already in Making Tax Digital for Income Tax and must maintain specified digital records and submit quarterly updates through compatible software. The applicable threshold is based on qualifying income under HMRC's rules and can take both property and self-employment income into account. A landlord should not assume MTD applies solely because the property generates a particular taxable profit figure; it is a different test.
Even landlords outside mandatory MTD should retain reliable source records. On disposal, purchase costs, improvements, ownership history, transaction costs and letting use may affect the gains calculation, and some UK residential property gains have a separate time-sensitive reporting requirement. Treat the property record as a lifecycle record from purchase to sale, not just a folder of yearly returns.
What useful property-accounting support looks like
A practical package begins with property-level rent and expense schedules, finance statements and reconciled records. It then distinguishes personal and corporate ownership, identifies allowable and non-allowable items, reviews MTD where applicable and maps the filing route. For a portfolio, periodic reporting should compare vacancies, repairs, finance and cash by property instead of presenting a single unsupported profitability percentage.
Britvex.co.uk has a dedicated landlord tax service connecting rental records, Self Assessment, digital requirements, non-resident issues and Capital Gains Tax. Its wider UK accountancy and tax hubs help clients link company, property and personal obligations. A first enquiry should include how the property is owned, location, rental periods, mortgage financing, relevant expenses and the next reporting deadline.
The landlord’s three parallel ledgers
For decision-making, it helps to distinguish a cash ledger, a tax-support ledger and a capital-history schedule. The cash ledger shows receipts, mortgage payments, repairs and available money. The tax-support ledger identifies reportable rental income and the costs or finance information relevant under the applicable rules. The capital schedule preserves acquisition, improvement and disposal costs that may matter on sale. These records overlap but are not interchangeable.
For a portfolio, the schedules should also be attributable to the legal owner and individual property. This helps explain why one property has poor cash conversion while another shows substantial taxable profit. Britvex Advisory's property tax work can connect these views to Self Assessment or company accounts without confusing cash expenditure with allowable tax costs.
When rising rent fails to improve the owner’s position
An increase in gross rent may be offset by higher financing costs, void periods, repairs, service charges and tax. A landlord should model both a cash sensitivity and an annual tax position before refinancing or making a major improvement. The assumptions should include whether the property is held personally, jointly or in a company and which finance-cost relief rules apply.
The key question is not simply whether rent covers the mortgage this month. It is whether the property produces sustainable after-cost cash, remains in a manageable maintenance condition and preserves appropriate records for future reporting. Avoid using a single headline “net yield” that excludes material financing or tax issues.
Illustrative rental calculation
Annual rental receipts of £18,000 less £3,500 of assumed qualifying running costs leaves £14,500 before applying special individual residential finance-cost rules. Deducting £6,000 of mortgage interest from cash leaves £8,500 cash before tax and principal repayments, but does not make taxable profit £8,500. A possible tax reducer depends on the full UK tax computation. Figures are educational only.
Operational readiness: evidence and the next decision
| Area | Evidence to review | Responsible action |
|---|---|---|
| Rent | Gross rent and agent deductions | Keep tenant and agent statements |
| Revenue costs | Repairs, insurance, fees subject to rules | Retain detailed invoices |
| Finance costs | Interest versus capital repayments | Apply ownership-specific tax treatment |
| Capital works | Improvements or acquisition costs | Record separately for later review |
| Reporting | Self Assessment, company accounts or MTD | Use the correct legal-owner route |
Explore related Britvex Advisory services
These are the relevant service routes for this specific topic. Choose the requirement that fits your situation, rather than treating every link as a service everyone needs.
Talk to Britvex Advisory about your UK accounting and tax requirements
Accountancy · Tax · Advisory · Compliance. Explain your business, the next filing or decision and the records available. Britvex can discuss the appropriate scope, onboarding and any identity checks required.
Primary: Britvex.co.uk · Secondary: Britvex.com · Client portal
Telephone: +44 20 3758 7500 · WhatsApp: +44 7757 698777 · Email: info@britvex.co.uk
Frequently asked questions
Why is rental taxable profit more than cash left after mortgage payments?
Loan capital repayments are not rental expenses, and individual residential-landlord finance-cost relief follows special tax-reduction rules.
Is all mortgage interest deductible from rental profit?
Not for individual residential landlords under the standard restricted finance-cost regime. Property companies can have different rules.
Can a non-resident landlord ignore UK tax?
No. UK rental income may remain taxable in the UK, and the Non-resident Landlords Scheme can affect payments.
Does MTD use taxable rental profit to determine the threshold?
The qualifying-income test has its own rules; taxable rental profit alone does not determine who must join.
Professional credentials and client responsibilities
BRITVEX ADVISORY LTD · UK Company No. 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervision XNML00000219568 · ICO registration ZA013667080 · HMRC Agent Services Account. These are different registration and access arrangements; neither government registration nor supervision is an endorsement or guarantee of professional outcomes. Client identity verification, correct authorizations and an agreed engagement scope may be necessary.
Current firm details: Britvex Advisory · Regulation and compliance · Company registration record.
Official reference points
Regulations and filing requirements should be checked against the applicable current official source for the individual case.
About the author — Syed Raheel Shahzad
Syed Raheel Shahzad — سيد راحيل شهزاد is an author, Founder & Group CEO of The Syed Group, and a business strategist, systems thinker and architect. The Group is the parent organization of Britvex Advisory Ltd, whose own UK professional-service and regulatory responsibilities remain separate.
Official author site · Coordinates of Thought — A Home for Philosophy · The Coordinates of Thought book.
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ.
His philosophical publishing program is represented in the separate structured-data catalogue and does not imply that these books are accounting service products.
The publishing organization is distinct from Britvex Advisory Ltd, the UK professional-services firm featured in this article. This article provides general information, not individualized tax, legal, investment or charity-accounting advice. Legal status, tax treatment and regulatory requirements depend on the actual facts and current rules. The author and publication are connected with The Syed Group and Coordinates of Thought through their documented identities.