Britvex: The Essential Accounting Records UK Landlords and Property Companies Should Maintain
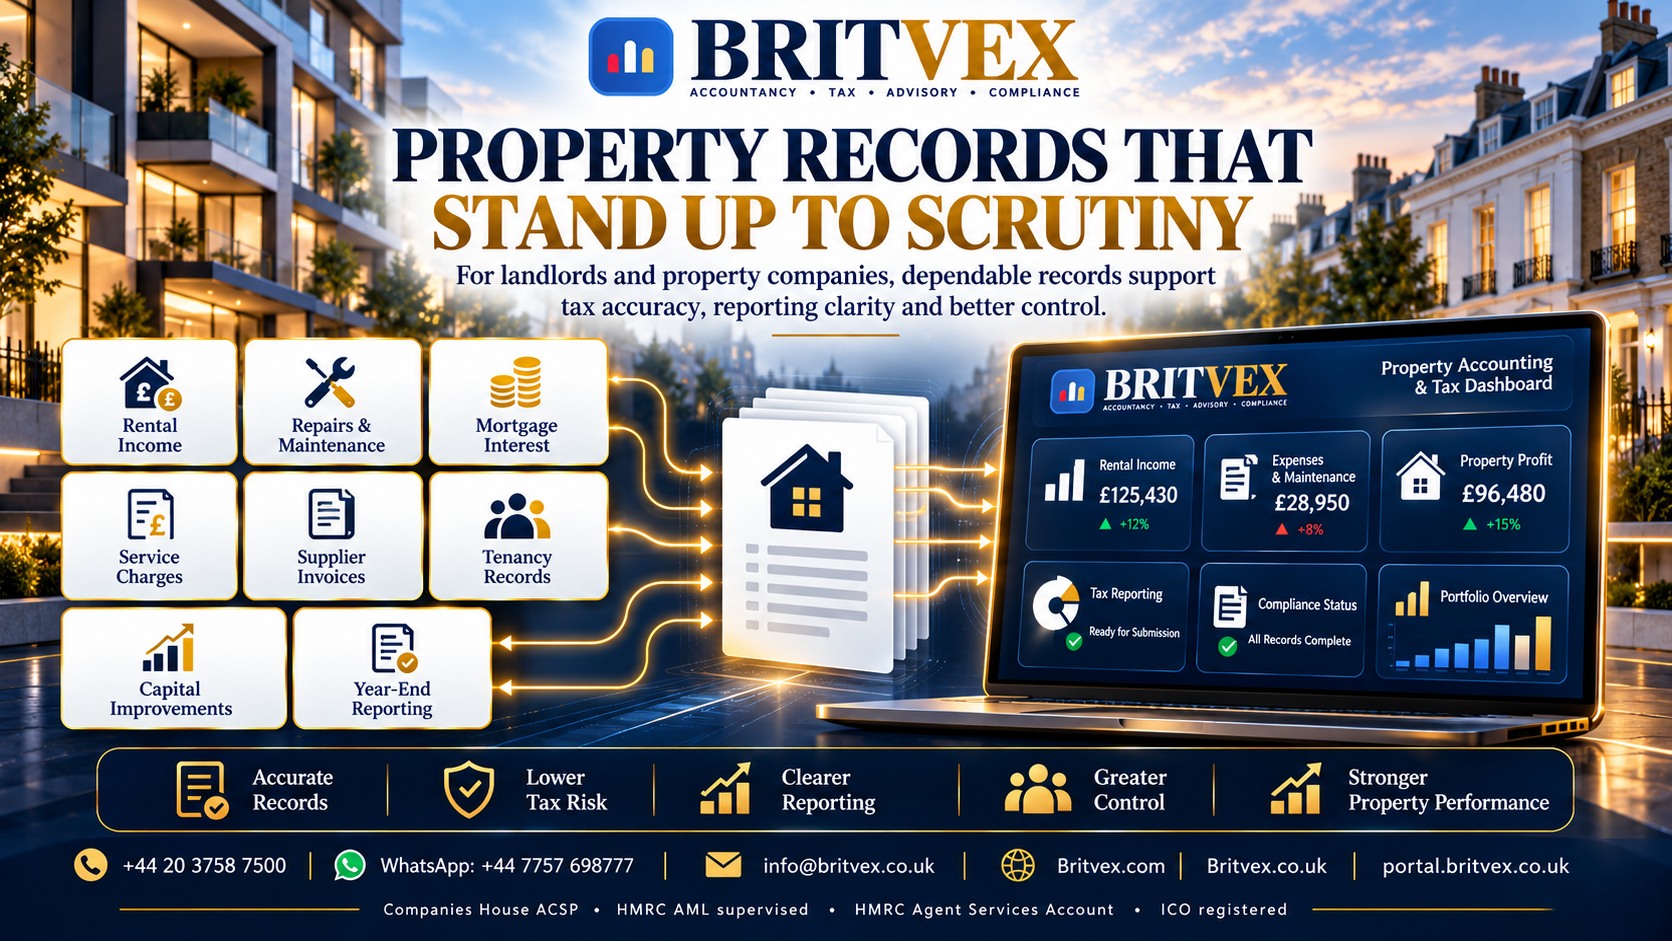
Landlords and property companies need records that distinguish gross rent, expenses, mortgage finance, capital works, deposits and the applicable personal or company tax route.
At a glance: Britvex explains rental income records, property expenses, mortgage interest treatment, repairs and tax reporting for UK landlords and property companies.
Britvex: Accountancy · Tax · Advisory · Compliance · Companies House ACSP · HMRC AML supervised · Client Portal
Rental income is not the whole property record
A landlord statement may show rent received but not the expenses, capital items, finance arrangements and deposit liabilities that determine the full picture. UK landlords and property companies should build a property-level record that can explain the amount earned and the treatment applied. A bank balance alone cannot distinguish rent, a refundable deposit, a property loan and an owner transfer.
Britvex's landlord tax and bookkeeping services are relevant to maintaining that record across the letting period.
Maintain records at the property and owner level
When a person owns several properties, records should identify which rent, invoice and cost belongs to which property, while still reconciling to the individual's or company's accounting position. Tenancy dates, agent statements, changes in occupancy and ownership interests can affect reporting. A property company needs its own books; an individual's personal rental business is not automatically a company.
Mixing personal, company and jointly owned properties in one unsplit spreadsheet can create errors that are hard to correct at year end.
Distinguish repair from capital improvement
A repair that restores an existing element and expenditure that creates an improvement can have different tax consequences. The label used by the contractor does not necessarily determine the treatment. The scope of works, condition before and after, evidence and applicable tax rules matter. Large refurbishment invoices should be reviewed rather than assigned to 'repairs' merely because they arrived during a tenancy.
Keeping photographs, scopes and invoices can assist classification, but this article does not determine deductibility in an individual case.
Finance costs need special attention
A mortgage statement can include capital repayments, interest, fees and other items. Treating the whole bank debit as a property expense is not generally correct. The rules for residential finance costs can differ for individual landlords and limited companies; eligibility and relief should be determined for the legal owner and relevant year.
Britvex can examine the actual statements and ownership before applying an expense category or tax calculation.
Property record categories and common tax-review questions
This working comparison is a practical starting framework. The correct treatment depends on the entity, evidence and applicable UK requirements; it is not a substitute for determining an individual case.
| Record | Why keep it | What not to assume |
|---|---|---|
| Gross rent and letting statements | Connect tenants, periods and receipts | Net agent remittance is not always gross rental income |
| Repairs and contractors | Assess expenses and property condition | Every refurbishment is a revenue repair |
| Mortgage and finance statement | Separate interest, fees and capital repayments | Whole mortgage payment is deductible |
| Improvements and acquisition | Preserve capital-cost history | All improvements reduce current-year rental profit |
| Tenancy and deposits | Explain occupancy and held funds | Deposit is immediately rental revenue |
| Sale and ownership records | Support eventual disposal tax analysis | Annual rent records replace disposal evidence |
Deposits, service charges and agent balances
Property records should show tenant deposits and the obligations attached to them separately from income where appropriate. Letting agents may deduct fees, repair costs or other charges before transferring cash to the landlord. Recording only the net payment can hide gross rent and expenses.
A monthly reconciliation can compare the tenancy schedule, agent statement, invoices and bank receipts, and preserve any difference for review.
Property tax also changes when the asset is sold
The documentation needed for a sale often begins years earlier, with acquisition costs, qualifying improvement expenditure, ownership changes and disposal proceeds. A sale may create Capital Gains Tax reporting duties on a distinct timetable, while a company may face Corporation Tax consequences. A rental-income return is not a substitute for reviewing the disposal.
Keeping long-term records through the whole asset lifecycle reduces later reconstruction and makes professional assessment more reliable.
Digital reporting depends on actual eligibility
Making Tax Digital for Income Tax has staged implementation thresholds and qualifying-income tests. A landlord should check whether the rules apply to them and when; ownership through a limited company is treated differently from an individual's property-income reporting. Property expenses and records must still be correct regardless of which software route is used.
Digital access can help remote landlords, but professional review remains important where ownership, residence or expense classification is complex.
A realistic property accounting control sheet
For each property, keep a schedule of rent due and received, tenancy changes, management fees, repairs, insurance, finance-cost statements, capital improvements, deposits, invoices and relevant tax records. Reconcile the totals to bank and agent statements. Record the source of every manual adjustment.
The objective is not to maximize the number of rows; it is to make an accurate year-end result possible without guessing where the money came from.
A landlord based outside the UK still needs to review UK rules
Overseas residence does not automatically remove UK tax responsibilities for UK rental income. The Non-resident Landlords Scheme and other reporting obligations may need attention. A landlord may have gross rental income received without deduction only where the relevant arrangement permits it; that does not necessarily mean tax is not due.
Britvex's landlord-tax service explains why residence, ownership, income and reliefs need to be considered together.
The Britvex approach to property records
Britvex can be consulted about how to organize property-level bookkeeping, identify the correct personal or company tax route and retain source records. The service should begin with the legal ownership and activity, not with a generic promise that every property cost is deductible.
A property ledger that stands up to scrutiny is one whose figures can be reconstructed from the underlying tenancy, agent, bank and invoice evidence.
Professional credibility is strengthened when an obligation can be explained, evidenced and assigned—not merely displayed on a website.
Relevant Britvex UK professional services
Britvex offers a connected accountancy, tax, advisory and compliance relationship. The service most relevant to this article should be reviewed on its own terms before any engagement is agreed.
Primary official website: Britvex.co.uk · Secondary official website: Britvex.com.
Related reference: Britvex Self Assessment tax return guide. This companion is supplied in the 20 October editorial draft; confirm its destination is published before enabling the link.
Frequently asked questions
Is the entire mortgage payment an allowable rental expense?
No. Capital repayments and finance costs must be distinguished; the relevant rules depend on ownership and circumstances.
Are improvements always deductible as repairs?
No. Classification can require detailed review of the property and actual works.
Do overseas landlords have UK reporting responsibilities?
They may. UK rental income and the Non-resident Landlords Scheme can require separate consideration.
Britvex Advisory — professional identity and client access
BRITVEX ADVISORY LTD · UK company number 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervised (XNML00000219568) · HMRC Agent Services Account established · ICO registered (ZA013667080).
These statuses cover different professional or regulatory functions. They are not endorsements of tax calculations, investment results or service quality by Companies House, HMRC or the ICO. Client authorization is required where applicable.
Britvex.co.uk · Britvex.com · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
Discuss your UK accounting or compliance question with Britvex
Tell Britvex what needs attention, the legal form involved and which records are available. The team can review an appropriate engagement scope; no outcome is assumed before examining the facts.
Contact Britvex Advisory → Britvex.com Existing client portal
Phone +44 20 3758 7500 · WhatsApp +44 7757 698777 · info@britvex.co.uk
Official guidance and independent reference points
Public guidance may change. Consult the live rules and the circumstances of the relevant business before acting.
Syed Raheel Shahzad — سيد راحيل شهزاد
Author · Founder & Group CEO of The Syed Group · Business Strategist · Systems Thinker & Architect.
SyedRaheelShahzad.com · CoordinatesOfThought.com — A Home for Philosophy
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ
His philosophical books and publishing work remain distinct from the professional services described in this article. The Syed Group publishes the author catalogue.
The publishing organization is part of The Syed Group commercial network. Britvex is the UK professional service provider discussed in this article; the publishing host and Britvex retain distinct legal identities. Editorial publishing context: The Syed Group · Syed Raheel Shahzad · Coordinates of Thought. © 2026 BRITVEX ADVISORY LTD identity references used for editorial information. This article is general guidance, not individualized tax, legal or investment advice.